Scott Bessent Declares Himself ‘The House,’ Dares Traders To Bet Against His Yen Gambit
Treasury Secretary Scott Bessent declared himself “the house” and dared currency traders to bet against his efforts to strengthen the Japanese yen Tuesday, arguing his position gave him an information advantage over the market.
Jack McGeever · Sep 9, 2026 · 3 min read
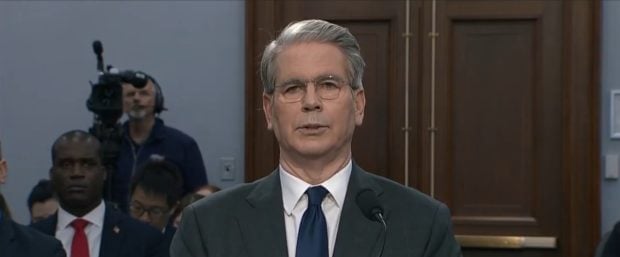

Treasury Secretary Scott Bessent declared himself “the house” and dared currency traders to bet against his efforts to strengthen the Japanese yen Tuesday, arguing his position gave him an information advantage over the market.
Bessent said at an event at SMU’s Cox School of Business that he had more access to information about U.S. and Japanese policy as Treasury secretary, which he argued gave him an advantage over traders betting against the yen. Bessent’s previous market interventions were questioned by investors, such as his August plan to double Treasury buybacks that have yet to yield fruit.
“I am the house now, so when we intervene with the Japanese yen, I have pretty good insight into what the Japanese, what the Bank of Japan is going to do, what Japanese policymakers are going to do,” Bessent said. “And you can bet against me if you want.”
Bessent, a former hedge fund executive, pointed to the rare joint U.S.-Japan intervention on July 31 to support the yen as an example of the advantage he now holds over traders. The Treasury sold euros and bought yen as the Japanese currency hovered near a 40-year low.
The yen has climbed more than 6% against the dollar since late July and reached about 153 per dollar Wednesday, its strongest level since February, as traders bet that the Bank of Japan will raise interest rates at its Sept. 17-18 meeting.
Higher Japanese rates could support the yen by making Japanese assets more attractive to investors, but the shift could create problems for the U.S.
Japanese investors held approximately $1.117 trillion in U.S. Treasury securities as of June, down from roughly $1.225 trillion in January. Japanese investors also sold a net ¥3 trillion, or $18.7 billion, of foreign bonds through Aug. 22, the largest year-to-date outflow since 2022.
If Japanese investors sell more Treasurys to take advantage of higher returns at home, the U.S. government could have to offer higher yields to attract other buyers. Treasury yields serve as benchmarks across the American financial system, meaning higher government borrowing costs can feed into mortgage rates, corporate debt and other forms of credit.
A stronger yen could also unwind the so-called carry trade. Investors borrowed yen at Japan’s low interest rates, converted the money into other currencies and bought assets that offered higher returns. Rising Japanese rates or a stronger yen could erase those profits and push investors to sell foreign assets to repay their loans.