

VIJAY JAYARAJ: New Study Sheds Light On How Many Have Suffered Due To Foolish Green Policies
A new report from McKinsey & Company, the “ Global Energy Perspective ,” lays bare what many of us – dismissed as “climate deniers” – have been asserting all along: Coal, oil and natural gas will continue to be the…
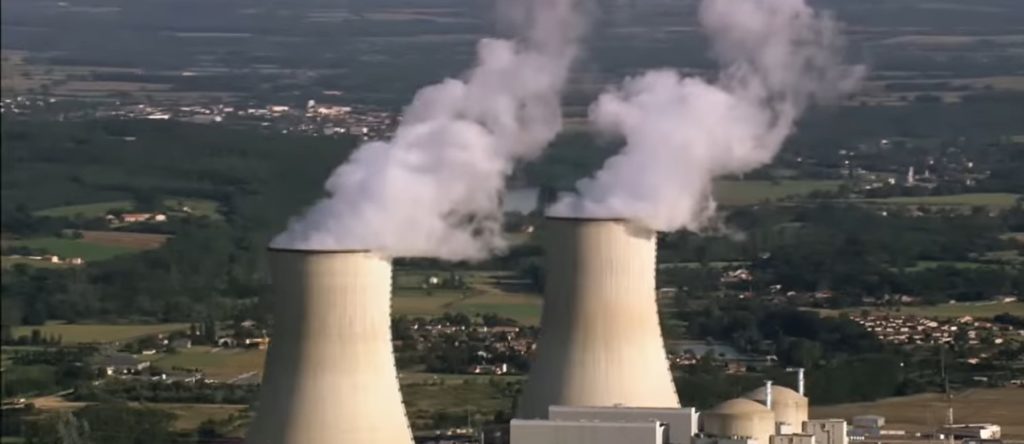
A new report from McKinsey & Company, the “Global Energy Perspective,” lays bare what many of us – dismissed as “climate deniers” – have been asserting all along: Coal, oil and natural gas will continue to be the dominant sources of global energy well past 2050.
The McKinsey outlook for 2025 sharply adjusts prior projections. Last year, the management consultant’s models had coal demand falling 40% by 2035. Today, McKinsey projects an uptick of 1% over the same period. The dramatic reversal is driven by record commissioning of coal-fired power plants in China, unexpected increases in global electricity use, and the lack of viable alternatives for industries like steel, chemicals and heavy manufacturing.
The report states that the three fossil fuels will still supply up to 55% of global energy in 2050, a forecast that looks low to me. Today’s share for hydrocarbons is more than 60% for electricity generation and more than 80% for primary energy consumption.
In any case, McKinsey’s report confirms what seasoned energy analysts and pragmatic policymakers have long maintained: The energy transition will not be swift, simple, or governed solely by climate targets. In fact, this energy transition will not happen at all without large scale deployment of nuclear, geothermal or other technological innovations that prove practical.
In places such as India, Southeast Asia and sub-Saharan Africa, the top energy priorities are access, affordability and reliability, which together add up to national security. Planners are acutely aware of a trap: Sole reliance on weather-dependent power risks blackouts, industrial disruption, economic decline and civil unrest.
That is why many developing nations are embracing a dual track: continued investment in conventional generation (coal, gas, nuclear) while developing alternative technologies. McKinsey says this in consultancy lingo: “Countries and regions will follow distinct trajectories based on local economic conditions, resource endowment, and the realities facing particular industries.”